By Global Consultants Review Team ,
India’s digital payments landscape is set for a change as the National Payments Corporation of India (NPCI) has announced a revised Merchant Discount Rate (MDR) framework for certain Unified Payments Interface (UPI) transactions.
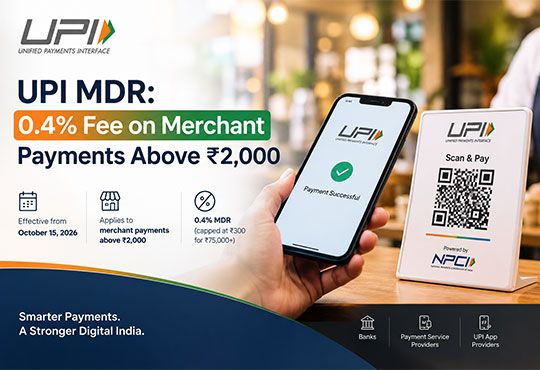
The new framework will take effect from October 15, 2026, and applies to specified person-to-merchant (P2M) payments above ₹2,000.
Under the framework, a 0.4% MDR will apply to eligible merchant transactions exceeding ₹2,000.
For transactions of ₹75,000 and above, the charge will be capped at ₹300 per transaction.
The fee is intended for the payment ecosystem participants, including banks, payment service providers and UPI application providers, rather than being collected as a government tax.
The change is focused on payments made by individuals to businesses, such as purchases at stores or payments to service providers.
Person-to-person transfers will remain free, and payments to merchants up to ₹2,000 will also remain free.
The Ministry of Finance has stated that approximately 96% of merchant transactions will remain unaffected.
Certain essential and thin-margin sectors, including railways, telecommunications, insurance, fuel and agricultural inputs, will have a flat MDR of ₹5 on eligible transactions above ₹2,000.
Payments relating to mutual funds, securities, stockbrokers and dealers will attract a separate rate of 0.02%, capped at ₹300 per transaction.
The government has clarified that customers will not pay the MDR directly.
The charge is applied within the merchant payment ecosystem and distributed among participating service providers. Small merchants covered by the zero-MDR framework will continue to receive exemptions.
The revised structure may require merchants, payment aggregators, banks and fintech companies to review their payment processes ahead of implementation.
Businesses may need to update billing systems, accounting workflows and payment technology to accommodate the new fee structure.
For merchants, the practical impact will depend on their transaction volumes, average payment values and eligibility for exemptions.
Larger retailers, online platforms and service providers may choose to absorb the processing cost, while others may review their operating expenses and payment arrangements.
The framework does not mean that every UPI payment will carry a fee.
For payment providers, MDR revenue may help support the infrastructure, service and security requirements associated with operating a large digital payments network.
The policy also places renewed attention on the financial sustainability of digital payment services while retaining free access for individuals and many everyday merchant transactions.
UPI has become a widely used payment method for everyday transactions, from small retail purchases to larger business payments.
The revised MDR framework introduces a differentiated fee structure while keeping person-to-person transfers and many low-value merchant payments free.
The October 15 implementation date gives businesses and payment service providers time to prepare for the revised arrangements.
As the framework takes effect, merchants and fintech companies will need to understand which transactions qualify, how fees are calculated and whether exemptions apply to their operations.
For consulting firms working with financial services, retail, fintech and digital transformation clients, the change may create demand for support in payment-system readiness, process reviews, cost analysis and technology updates.
The broader development highlights how changes in digital payment policy can affect businesses across the payments ecosystem.
We use cookies to ensure you get the best experience on our website. Read more...